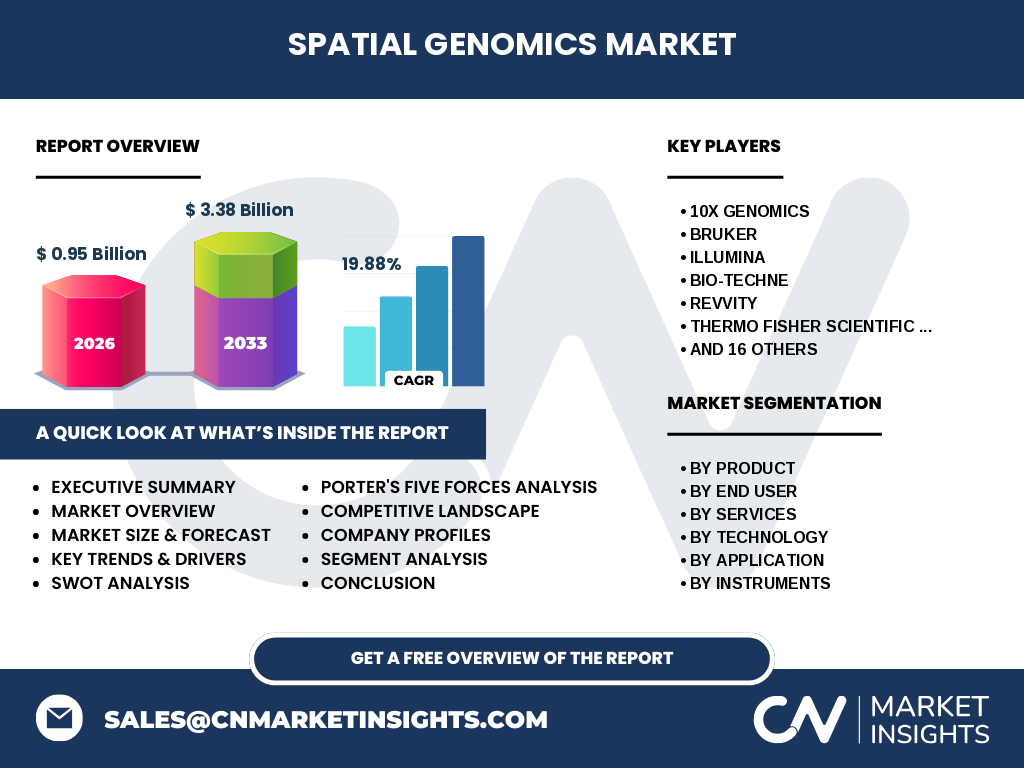
Market overview of the Spatial Genomics Market
The Spatial Genomics Market is valued at $0.95 billion in 2026, establishing a critical foundation for high-resolution cellular architecture studies. Our analysis indicates this sector bridges genomics and pathology, enabling researchers to visualize molecular profiles within native tissue architecture. Key innovators like 10x Genomics and Vizgen drive commercial expansion by offering platforms that map transcripts and proteins directly inside intact biological samples.
Structural Growth Drivers and Market Constraints
Growth is heavily propelled by rising investments in oncology and neuroscience research, alongside breakthroughs in high-throughput spatial transcriptomics and spatial proteomics. However, the market faces notable restraints, including prohibitive equipment costs and complex bioinformatics bottlenecks. Regulatory scrutiny from bodies like the FDA regarding diagnostic claims adds compliance hurdles, favoring well-capitalized firms capable of streamlining clinical translation for hospital laboratories.
Emerging Trends in the Spatial Genomics Industry
A profound shift toward multiomics integration is redefining the Spatial Genomics Market industry trends. Researchers increasingly demand platforms capable of simultaneous DNA, RNA, and protein analysis from a single tissue section. Companies such as Pixelgen Technologies AB and Curio Bioscience are capturing market share by deploying innovative microfluidic chips and advanced cloud-based analysis tools to handle massive spatial datasets.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic initially disrupted supply chains for specialized assay kits and delayed academic procurement cycles. However, our research shows it catalyzed remote bioinformatics innovations and accelerated infectious disease applications. Post-pandemic recovery has been robust, as pharmaceutical companies redirected capital toward automated slide processing systems and robust tissue preparation reagents to decode complex viral host-pathogen interactions.
Competitive Benchmarking and Market Concentration
The Spatial Genomics Market exhibits moderate concentration, dominated by major instrument manufacturers like Thermo Fisher Scientific Inc., Danaher Corporation, and Illumina. These established players compete aggressively with agile disruptors like Resolve Biosciences and RareCyte through strategic acquisitions, proprietary probe sets, and expanding sequencing platforms to capture high-margin consumable recurring revenue streams.
Executive Summary: Key Findings
Our comprehensive Spatial Genomics Market analysis projects the sector to expand from $0.95 billion in 2026 to reach $3.38 billion by 2033 at a remarkable CAGR of 19.88%. This rapid scaling underscores the transition of spatial biology from niche academic discovery to mainstream clinical diagnostics, fundamentally altering pharmaceutical drug development pipelines.
Market Forecast from 2027 to 2033
Driven by escalating demand for precision medicine, the Spatial Genomics Market market size is set for exponential gains. Based on our research, the 2027-2033 trajectory will be anchored by widespread adoption of spatial imaging systems and artificial intelligence-based analytical tools, pushing commercial valuation past the $3.38 billion threshold by the end of the forecast period.
Segmentation Analysis of Products and Technologies
The ecosystem is deeply categorized by instruments, consumables and reagents, software, and specialized services. Technological adoption centers on Spatial Transcriptomics and Fluorescence In Situ Hybridization. Consumables—specifically assay kits and barcoding reagents—generate the highest recurring revenue, benefiting specialized providers like Bio-Techne and Agilent Technologies Inc. within diagnostic laboratories.
Regional Market Analysis and Geographic Distribution
North America commands the largest share of the Spatial Genomics Market, bolstered by robust NIH funding and heavy concentration of biotech firms. Europe follows closely, driven by stringent European Medicines Agency frameworks and collaborative academic consortia. Meanwhile, Asia-Pacific emerges as the fastest-growing region, powered by surging genomics investments in China and Japan led by entities like BGI Genomics and MGI Tech.
In-Depth Regional Review and Localized Constraints
Regional performance highlights distinct adoption patterns. North American laboratories rapidly integrate multiomics integration platforms, whereas European institutions prioritize translational oncology applications. APAC growth faces localized supply chain constraints for specialized laser capture microdissection instruments, yet regional government initiatives continue to stimulate local biomanufacturing and academic research infrastructure.
Strategic Positioning of Leading Companies
Industry leaders maintain competitive moats through comprehensive product portfolios. 10x Genomics anchors its dominance in high-throughput transcriptomics, while Bruker and Carl Zeiss AG leverage decades of microscopy expertise to deliver superior spatial imaging systems. Companies like Revvity and Arima Genomics focus on specialized sample preparation and chromosomal conformation assays to secure indispensable workflows.
Porter's Five Forces Assessment
Competitive rivalry is intense as established life science giants acquire innovative startups to secure next-generation IP. Supplier power remains moderate due to specialized microfluidic chips and barcoding reagent requirements. Meanwhile, threat of substitutes is low, as traditional bulk sequencing cannot replicate single-cell spatial resolution.
SWOT Analysis of the Spatial Genomics Sector
Strengths include unprecedented cellular resolution and deep biomarker discovery potential. Weaknesses involve high instrumentation costs and complex data interpretation workflows. Opportunities lie in expanding clinical diagnostics applications, while threats stem from stringent data privacy regulations and intellectual property litigation among key market players.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from raw chemical and biochemical suppliers to assay developers, instrument manufacturers, and ultimately to pharmaceutical and biotechnology companies. Value creation concentrates heavily in proprietary barcoding reagents and cloud-based analysis software, where firms like BioTuring Inc. and Dovetail Genomics capture substantial margins.
Investment Insights and High-Potential Areas
Strategic investors should prioritize firms specializing in artificial intelligence-based analytical tools and automated slide processing systems. As laboratories demand streamlined workflows, companies capable of bridging multiomics integration services with clinical trial pathology will yield the highest risk-adjusted returns through 2033.
Conclusion and Key Takeaways
The Spatial Genomics Market represents a transformative frontier in life sciences. Achieving a projected $3.38 billion by 2033 at a 19.88% CAGR, the sector rewards organizations that successfully integrate hardware precision with scalable bioinformatics software, cementing spatial biology as a cornerstone of modern molecular medicine.
Research Methodology and Data Triangulation
Baseline estimates are meticulously triangulated by combining global trade registry data, primary stakeholder interviews with key opinion leaders, and secondary macroeconomic indicators. Our analysts cross-reference corporate financial filings, regulatory submissions with bodies like the EMA and FDA, and proprietary shipment tracking to ensure precise market sizing.
Scope of the Report and Coverage Parameters
This report covers the global Spatial Genomics Market across major product categories, application verticals including oncology and neuroscience, and key geographic regions. Limitations include macroeconomic volatility impacting venture capital funding and localized regulatory delays affecting clinical adoption timelines in emerging markets.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum highlights aggressive co-development partnerships and platform launches. Market participants routinely forge alliances to combine multiplexed imaging with advanced bioinformatics software. Companies like Singleron Biotechnologies Ltd. and S2 Genomics actively expand their global footprint through strategic distribution agreements, addressing escalating demand for high-resolution single-cell analysis.